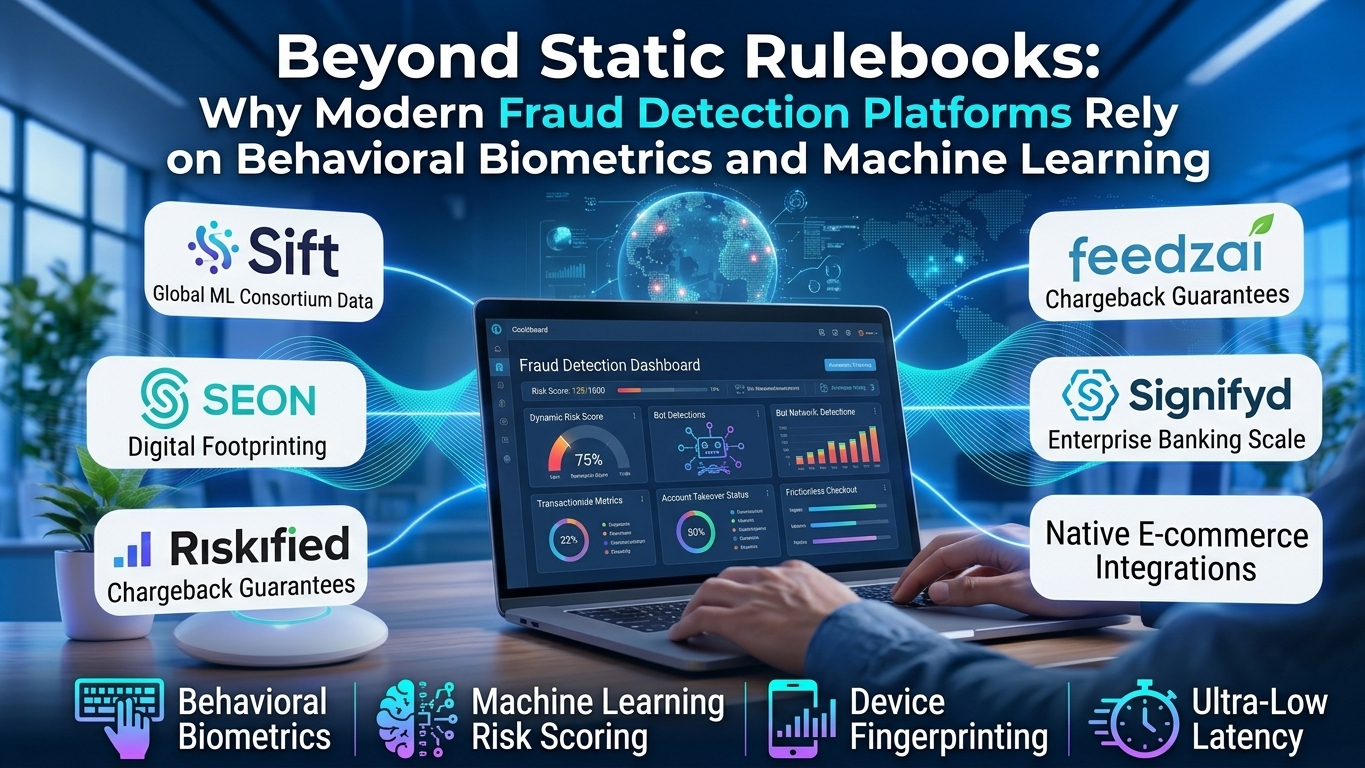
Digital commerce, online banking, and peer-to-peer payments operate at a blistering pace, offering customers instantaneous transactions with a single click. Unfortunately, cybercriminal syndicates and automated bot networks operate with that exact same speed. When financial institutions and e-commerce merchants rely on legacy, static rule-based fraud filters—such as blocking transactions solely based on geographic location or mismatched card security codes—they invariably trigger a high volume of false positives that frustrate legitimate customers, while sophisticated fraudsters easily bypass the rules using stolen credentials and synthetic identities.
Fraud Detection Platforms (FDP) combine machine learning, behavioral biometrics, device fingerprinting, and global consortium threat intelligence to identify and block fraudulent transactions in milliseconds. Selecting the right fraud prevention platform requires balancing high-speed decisioning accuracy with low customer friction.
Understanding the Anatomy of Modern Digital Fraud
Fraud detection software encompasses enterprise platforms designed to analyze user behavior, device telemetry, and transactional data in real time to prevent financial crime, account takeovers (ATO), and payment fraud.
Unlike traditional back-office risk reviews that occur hours or days after a transaction, modern fraud platforms operate inline during checkout or login, rendering instantaneous accept, decline, or step-up authentication decisions.
A professional fraud detection architecture typically governs several critical operational phases:
- Device Fingerprinting and Contextual Telemetry: Analyzing hardware identifiers, IP reputation, proxy usage, and browser characteristics to detect emulators, bots, or device spoofing.
- Behavioral Biometrics: Measuring subtle human interaction patterns—such as typing cadence, mouse movement velocity, and swipe angles—to verify that a genuine human user is operating the account.
- Machine Learning Risk Scoring: Processing thousands of transactional data points instantly through predictive models trained on global fraud patterns to assign a dynamic risk score.
- Case Management and Manual Review: Routing borderline transactions to human fraud analysts with clear explanatory dashboards and risk indicators.
The fundamental objective is to stop professional fraudsters instantly while ensuring legitimate customers experience zero friction during checkout or onboarding.
Key Evaluation Criteria for Fraud Detection Platforms
Selecting an enterprise fraud platform requires examining scoring latency, machine learning adaptability, and false-positive minimization.
Ultra-Low Decision Latency
In e-commerce and payment processing, every millisecond matters. An effective fraud platform must ingest telemetry, evaluate risk models, and return a decision in under a hundred milliseconds to prevent shopping cart abandonment.
Consortium Data and Global Threat Intelligence
Standalone fraud tools only see transactions occurring within a single merchant’s ecosystem. Leading platforms leverage massive global consortium networks, pooling anonymized threat data across millions of global merchants to recognize professional fraud rings immediately.
Custom Rule Builders and Machine Learning Control
While machine learning models excel at catching unknown fraud patterns, fraud analysts must also be able to deploy custom business rules quickly (such as temporarily blocking specific high-risk prepaid card bins during an active attack wave).
Leading Fraud Detection Platforms and Software Solutions
The fraud detection software market features dedicated fintech security innovators alongside comprehensive enterprise payment risk platforms.
Sift (Sift Science)
Sift is an industry-leading digital trust and safety platform that leverages global machine learning networks to protect e-commerce, fintech, and travel enterprises from payment fraud and account takeovers.
- Primary Focus: Real-time machine learning fraud prevention, payment protection, and account takeover defense.
- Deployment Model: Cloud-native SaaS platform with flexible REST APIs and mobile SDKs.
- Significant Advantage: Massive global data network (Sift Global Data Network) that shares fraud patterns instantly across thousands of connected digital brands.
- Important Limitation: Advanced customization of custom machine learning models requires technical data science resources.
SEON
SEON provides a modern, agile fraud prevention platform renowned for its innovative digital footprinting and open-API architecture, making it exceptionally popular among fast-growing fintechs and crypto platforms.
- Primary Focus: Digital footprint analysis, social profiling, and flexible API-driven fraud scoring.
- Deployment Model: Cloud SaaS platform with lightweight API integration.
- Significant Advantage: Unmatched ability to assess user risk by analyzing digital footprints (social media accounts linked to email addresses and phone numbers) instantly.
- Important Limitation: Highly customized enterprise workflows or complex multi-entity governance structures may require supplementary tuning.
Riskified
Riskified offers a fully outsourced, guaranteed chargeback fraud prevention solution, taking on financial liability for fraudulent transactions it approves.
- Primary Focus: Guaranteed e-commerce fraud prevention, chargeback protection, and conversion rate optimization.
- Deployment Model: Cloud SaaS platform with end-to-end liability shift.
- Significant Advantage: Eliminates chargeback risk entirely by reimbursing merchants directly for fraudulent transactions approved by the platform.
- Important Limitation: Transaction-based pricing model can be more costly than software-only licensing tiers.
Feedzai
Feedzai delivers enterprise-grade risk management and fraud prevention tailored specifically for major banking institutions, payment networks, and large-scale fintechs.
- Primary Focus: Banking fraud prevention, anti-money laundering (AML), and real-time transaction monitoring.
- Deployment Model: Cloud SaaS or hybrid enterprise deployment.
- Significant Advantage: Exceptional scalability and advanced artificial intelligence engineered to handle high-volume banking rails and instant payment networks.
- Important Limitation: Enterprise architecture and implementation complexity are over-engineered for standard e-commerce merchants.
Signifyd
Signifyd provides automated commerce protection and guaranteed fraud prevention, helping major brands eliminate chargeback losses and streamline order fulfillment.
- Primary Focus: Guaranteed payment fraud protection and automated order fulfillment workflows.
- Deployment Model: Cloud SaaS platform integrated with major e-commerce platforms (Shopify, Magento, BigCommerce).
- Significant Advantage: Deep native integrations with leading e-commerce engines and comprehensive financial guarantees against fraudulent chargebacks.
- Important Limitation: Custom non-e-commerce applications (such as proprietary SaaS subscription billing) require more custom API integration work.
Platform Comparison Overview
| Product | Primary Focus | Deployment Model | Significant Advantage | Important Limitation |
| Sift | Global machine learning fraud detection and ATO defense | Cloud SaaS / API | Massive global consortium data network sharing real-time threat intelligence | Complex custom model tuning requires data science expertise |
| SEON | Digital footprinting and flexible API fraud scoring | Cloud SaaS / API | Innovative social and digital footprint analysis from simple identifiers | Complex enterprise multi-entity setups need careful tuning |
| Riskified | Guaranteed e-commerce chargeback protection | Cloud SaaS (Liability Shift) | Takes 100% financial liability for approved fraudulent orders | Transaction-based pricing can carry higher costs |
| Feedzai | Enterprise banking fraud and instant payment monitoring | Cloud / Hybrid | Exceptional AI scale built specifically for major financial institutions | Implementation complexity is over-engineered for standard retail |
| Signifyd | Automated e-commerce protection and guarantees | Cloud SaaS / E-commerce | Deep native shopping cart integrations and financial guarantees | Custom non-retail applications require bespoke API integration |
Operational Risks and Common Pitfalls
Implementing a fraud detection platform without careful calibration introduces severe business friction.
High False-Positive Rates Damaging Revenue
Setting fraud thresholds too aggressively blocks legitimate customers at checkout, directly harming conversion rates and driving frustrated buyers to competitors.
Ignoring Account Takeover (ATO) Vectors
Focusing exclusively on credit card payment fraud while ignoring account takeovers leaves organizations vulnerable to attackers stealing existing user balances and loyalty points.
Over-Reliance on Static Rules
Failing to update machine learning models and relying solely on static rules allows sophisticated fraudsters utilizing synthetic identities and automated bots to bypass defenses easily.
Questions to Guide Vendor Selection
Before procuring a fraud detection platform, risk managers, e-commerce directors, and Chief Information Security Officers should address several critical operational questions:
- What is the platform’s average decision latency, and can it evaluate transactions within millisecond checkout windows?
- Does the vendor offer a financial liability guarantee (chargeback reimbursement), or does the organization absorb all fraud losses?
- How comprehensive is the platform’s consortium data network in recognizing international fraud rings and emerging attack vectors?
- How easily does the software integrate with our existing payment gateways, e-commerce platforms, and customer management systems?
Making the Final Decision
Choosing a fraud detection platform depends heavily on an organization’s industry, transaction volume, and risk appetite.
E-commerce merchants seeking guaranteed financial protection against chargebacks frequently choose liability-shift platforms like Riskified or Signifyd. Conversely, digital marketplaces and fintechs managing complex account ecosystems and high transaction volumes benefit greatly from machine learning platforms like Sift or SEON, while major banking institutions rely on robust enterprise engines like Feedzai.
Ultimately, modern fraud detection platforms strike the delicate balance between impenetrable security and frictionless customer experience, protecting enterprise revenue without alienating genuine buyers
